
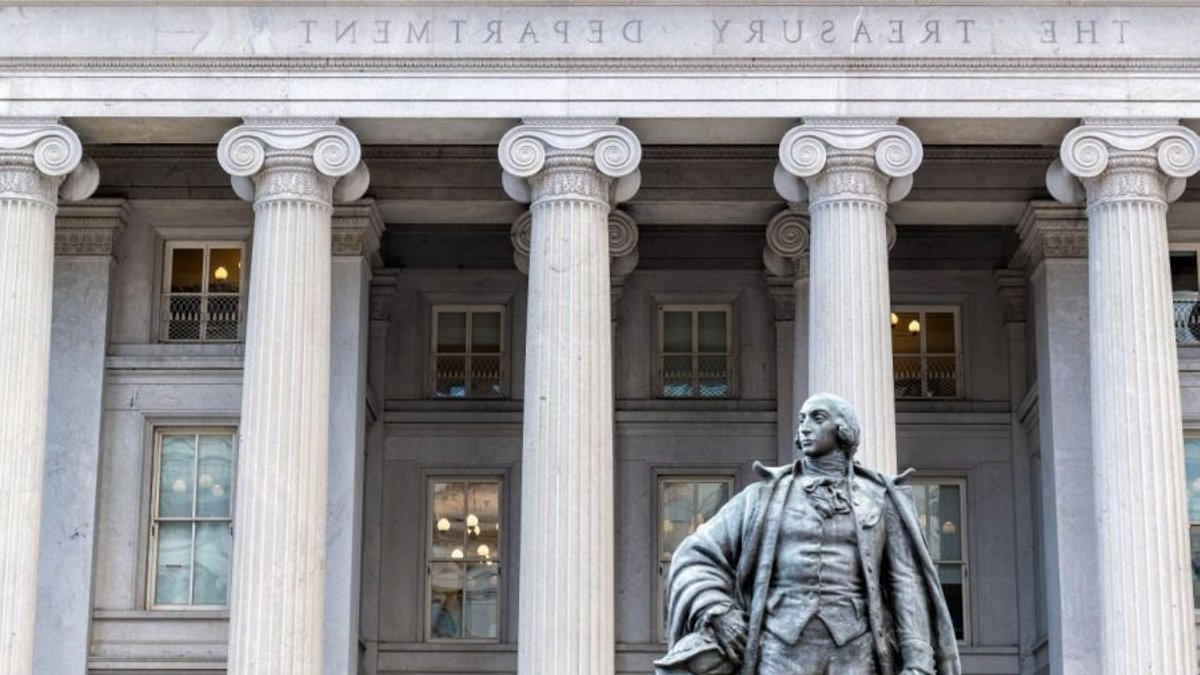
The Treasury’s recent bond‑buyback program has drawn sharp disagreement among Wall Street strategists, with some seeing a modest fiscal boost while others warn of hidden costs for future investors.
Investors watch closely.
Program expansion follows record‑high yields
On August 19, the Treasury announced it would double a program that purchases older, less‑traded government bonds, targeting $4 billion per operation in 10‑ to 30‑year issues, according to Thornburg Investment Management. The move came after the 30‑year Treasury yield rose to 5.34%, the highest level in almost two decades.
Official statements describe the effort as a liquidity measure intended to smooth trading in these securities, not as a rate‑management tool. Yet the timing has sparked debate about the administration’s broader fiscal strategy.
Contrasting views on fiscal impact
David Zervos, chief market strategist at Jefferies Financial Group, argues the buybacks act like a mild stimulus. He notes many older Treasurys with low coupons trade at 50‑70 cents on the dollar, so buying back $100 of face value for roughly $60 lets the Treasury retire debt at a discount, freeing balance‑sheet capacity for marginal spending.
JPMorgan Chase strategists counter that the practice could raise long‑term borrowing costs. If investors come to expect Treasury intervention whenever yields climb, they may demand higher yields to offset perceived predictability, potentially eroding confidence in the market.
Broader debt context
Macquarie Group pushes back against a “doom loop” narrative that links rising debt to runaway yields. It points out that U.S. debt‑to‑GDP has hovered around 3.4 times output for more than a decade, while strong corporate and household balance sheets provide a counterweight.
Thornburg’s own analysis falls between the extremes. Portfolio manager Brian McMahon says that making short‑term borrowing more expensive can cause more fiscal damage than a modest dip in long‑bond yields.
The firm manages two active bond ETFs that aim to address the market imbalance. The Thornburg Core Plus Bond ETF (TPLS) holds about $14.76 million in assets and posted a 30‑day SEC yield of 4.5% as of August 31. Its larger sibling, the Thornburg Multi‑Sector Bond ETF (TMB), contains $258.8 million and reported a 4.6% yield for the same period. Both funds benchmark against Bloomberg indices and charge expense ratios of 0.45% and 0.55% respectively.
Market reaction and a brief comparison
After the buyback announcement, long‑term yields initially fell but the decline quickly reversed as investors refocused on inflation, deficits, and the upcoming supply of government debt. Such swings are exactly what active managers monitor.
Historically, similar buyback efforts have produced mixed outcomes. For instance, the 2011 Treasury program, launched amid fiscal concerns, temporarily eased yield pressure but did not prevent a longer‑term upward trend. That pattern suggests the current effort may offer short‑term relief without guaranteeing lasting stability.
Thornburg’s data shows the Treasury’s balance‑sheet relief is limited. Funding purchases with new debt issued at higher yields can make the fiscal picture appear better than it truly is, a nuance that some market participants may overlook.


Leave a Reply